CoinPulse
Curve
Decentralized exchangeSwitzerland· founded 2020

What Is Curve Finance? The Stablecoin DEX, crvUSD and the Curve DAO

Curve Finance is a decentralized exchange built for swapping assets that should trade at nearly the same price: one dollar stablecoin for another, or a staked-ETH token for ETH. Its pools concentrate liquidity around that shared price, so these swaps move the price less than they would on a general-purpose exchange 1. Michael Egorov created Curve. The exchange launched in January 2020, and the CRV token followed in August 2020 1213. Curve has since added crvUSD, its own crypto-backed stablecoin, along with lending markets and a savings vault 16. Holders who lock CRV as veCRV govern the protocol 15. Curve doesn't take custody of user funds 17.

Facts checked 18 cited sources No score on this page, no affiliate links

At a glance

What it is
Non-custodial DEX for pegged assets, plus the crvUSD stablecoin and lending markets
Launched
DEX January 2020; CRV token August 2020; created by Michael Egorov 1213
Legal operator
None named on curve.finance, which describes itself as an interface to Curve's contracts (as of October 2026) 18
Governance
Curve DAO, voting with veCRV (CRV locked for 1 week to 4 years) 15
Networks
18 networks across CRV, crvUSD and scrvUSD; crvUSD minting on Ethereum only 14
Tokens
CRV (max ~3.03B) 12; crvUSD stablecoin 16
Custody
None; core pool contracts are immutable 17
Official site
curve.finance (documentation at docs.curve.finance). The old curve.fi domain was the target of DNS attacks in 2022 and 2025 69

How Curve's pools work

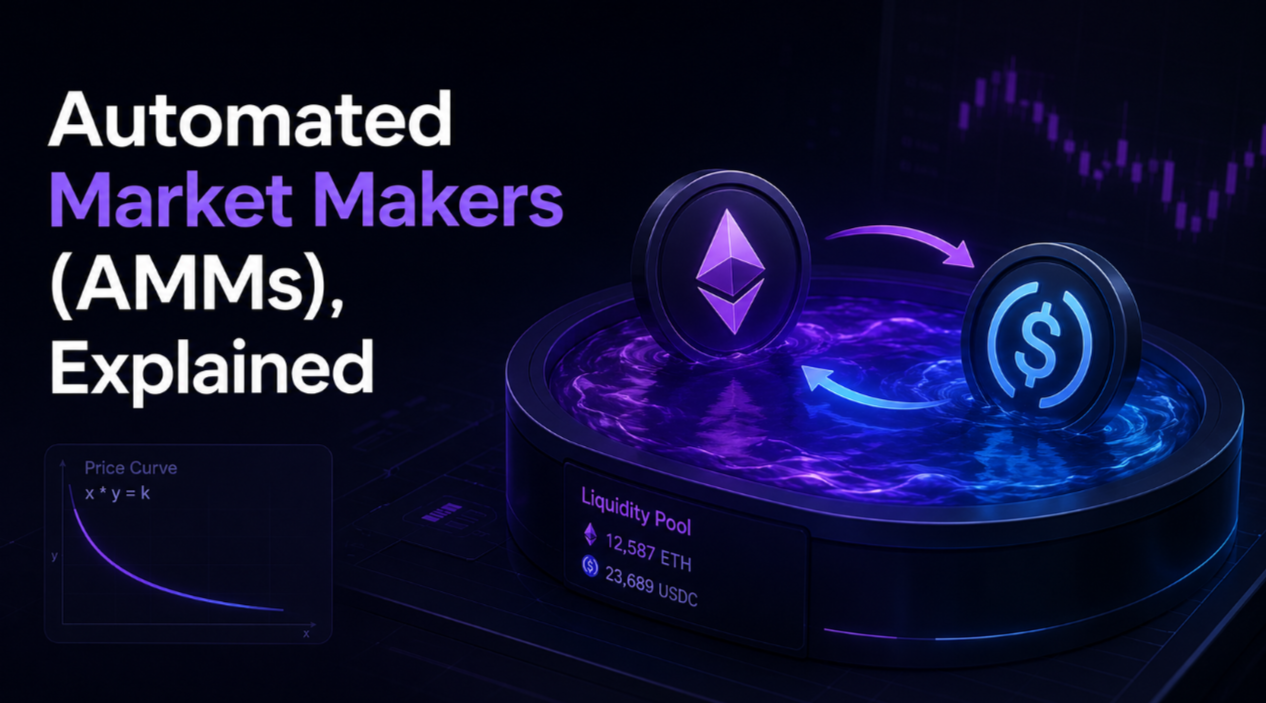
A standard AMM prices two tokens along a curve that allows any price ratio, so most of its liquidity sits at prices that rarely trade (how AMMs work). Curve's original StableSwap design mixes a constant-sum formula, which keeps the price close to 1:1, with a constant-product formula, which takes over as a pool becomes unbalanced. Liquidity ends up clustered around the peg 1. Curve later added pools for volatile pairs, and today's pool families are Stableswap-NG, Twocrypto-NG and Tricrypto-NG 1017.

A pool often holds several assets, for example three stablecoins. Liquidity providers (LPs) deposit one or more of them and receive an LP token. That token earns trading fees and, in pools that the DAO's gauge votes direct emissions to, CRV rewards 15.

One thing LPs in a stablecoin pool should understand: if one coin in the pool loses its peg, traders swap it into the pool for the healthy coins. LPs end up holding mostly the failing asset (stablecoin depeg risk).

Fees and where they go

Each Curve pool charges its own swap fee, and the swap screen shows it. Curve's fee map sets out where that money goes (as of October 2026) 10:

  1. Half the swap fee stays with LPs; half is the "admin fee." On Stableswap-NG, Twocrypto-NG and Tricrypto-NG pools, 50% of the swap fee is collected as an admin fee 10.
  2. Admin fees are converted to crvUSD. On Ethereum and Gnosis, burner contracts sell the collected tokens through CowSwap orders. Other chains burn fees locally and bridge the proceeds to Ethereum 11.
  3. Ten percent goes to the DAO treasury, 90% to veCRV holders 10. A FeeDistributor contract on Ethereum pays veCRV holders in crvUSD; it paid in 3CRV until a DAO vote changed this. Each week's revenue becomes claimable shortly after Thursday 00:00 UTC 11.
  4. crvUSD borrow interest is split too. A dynamic share, shown as about 15%, goes to scrvUSD savers. The rest, about 85%, joins the same revenue path 10.

Network gas comes on top, and it costs far more on Ethereum mainnet than on the layer-2 deployments.

CRV, veCRV and the Curve DAO

CRV is Curve's governance and reward token. Its maximum supply is about 3.03 billion, and issuance falls 16% every August. The roughly 1.7 billion tokens not yet issued go to liquidity providers over about 200 years 12. Holding CRV alone gives no vote. Holders lock it to receive veCRV:

  • Locks run from one week to four years. Longer locks give more veCRV, and the balance declines linearly to zero at expiry, when the CRV can be withdrawn 15.
  • veCRV can't be transferred 15.
  • veCRV earns its share of fees and crvUSD interest, boosts the holder's CRV rewards on their own liquidity positions, and votes on proposals and gauge weights, which decide where new CRV emissions go 15.

Core pool contracts can't be changed. The DAO controls parameters, new collateral types, gauges and crvUSD monetary policy. A separate Emergency DAO, a 5-of-9 multisig, holds narrowly limited emergency powers 1617. See how DAOs work.

crvUSD, scrvUSD and LlamaLend

crvUSD is a crypto-collateralized stablecoin. Users mint it by borrowing against assets such as ETH or BTC on Ethereum, and it can then be bridged to other networks 1416. Its liquidation design differs from most lending protocols. As collateral falls in value, the system (LLAMMA) gradually converts it into crvUSD across a price band rather than liquidating it all at once. That "soft liquidation" has costs: losses from those conversions don't reverse if the price recovers, and borrowers can't add or withdraw collateral while it is underway. If the loan's health reaches zero, a hard liquidation takes the collateral permanently 16. Peg support relies partly on PegKeeper reserves paired with USDT and USDC 16 (USDC issuer, USDT issuer). Borrow rates float under a DAO-set monetary policy 16.

scrvUSD is a savings vault: deposit crvUSD and earn part of the system's borrow interest 1016. LlamaLend runs isolated lending markets, including markets where CRV itself is collateral. The founder-loan liquidations of June 2024 (see below) played out partly in those markets 8. For background, see fiat-backed vs crypto-backed stablecoins.

Custody, security and risk

Curve doesn't hold user funds, and core pools are immutable 17. Its contracts have been audited repeatedly since 2020 by Trail of Bits, Quantstamp, MixBytes, ChainSecurity and StateMind 17. Curve's record shows where risk has come from in practice:

  • Toolchain risk. The 2023 exploit came from a bug in the Vyper compiler, not in Curve's pool logic 3.
  • Front-end risk. Attackers have hijacked the old curve.fi domain twice to serve a fake site that requested malicious approvals 69. Type curve.finance yourself and check every approval (crypto phishing).
  • Concentration risk. In June 2024, very large CRV-backed loans held by Curve's founder were liquidated across five protocols at once, and the size of those positions left about $10 million of bad debt 8.
  • Depeg and crvUSD risks. Depegs hurt LPs in pegged-asset pools. crvUSD borrowers face soft- and hard-liquidation losses and oracle lag 16.

Vulnerability reports go to [email protected] 17.

Incident record

3 partly recovered1 outcome unclear

The curve.fi domain was hijacked at the DNS level and served a spoofed site that asked users to approve a malicious contract

August 9, 2022partly recovered
Curve reverted it in about an hour, though DNS propagation took longer. Smart contracts were not affected. The registrar cited DNS cache poisoning 67.
Outcome
Partial recovery (user-side front-end attack)
Loss
~$570K from users who approved during the window
Recovered or reimbursed
112 ETH frozen by FixedFloat
Source: curve.substack.com

A reentrancy-guard bug in Vyper 0.2.15, 0.2.16 and 0.3.0 let attackers and frontrunning bots drain four Vyper-based pools

July 30, 2023partly recovered
JPEG'd pETH/ETH lost ~$11M, Metronome msETH/ETH ~$3.4M in ETH and msETH, Alchemix alETH/ETH ~$22.6M in ETH and alETH, and Curve's CRV/ETH ~$19.3M in CRV and WETH 23.
Outcome
Partial recovery
Loss
Over $61M in total
Recovered or reimbursed
Alchemix: all funds returned (Aug 5, 2023). JPEG'd: 5,495.4 WETH returned, with a 610.6 WETH bounty paid. Metronome: "a significant portion". CRV/ETH: 2,879.54 ETH (~$5.4M) returned by an MEV bot operator; the main CRV/ETH exploiter did not return funds, and Curve posted a $1.85M bounty for information
Source: hackmd.io

Not a hack

June 13, 2024partly recovered
Egorov's ~$95.7M of stablecoin loans, backed by ~$141M of CRV across five lending protocols, were liquidated as CRV fell more than 28% in a day 8.
Outcome
Partial recovery (bad debt; Curve's contracts not exploited)
Loss
~$10M of bad debt, mostly on LlamaLend
Recovered or reimbursed
Egorov said he had repaid 93%
Source: cointelegraph.com

Curve's X account was hijacked to post a wallet-drainer link

May 2025outcome unclear
Days later, on May 12–13, the curve.fi domain was compromised at the DNS layer. Curve said its protocol and contracts were unaffected and moved users to curve.finance 9.
Outcome
No confirmed loss (front-end/social compromise)
Loss
No user losses quantified in reporting
Recovered or reimbursed
n/a
Source: theblock.co

Hacks in DefiLlama’s public database are also scored as the security record on the Curve rating page.

Questions about Curve

Is curve.fi still Curve's website?
Use curve.finance. After the curve.fi domain was compromised at the DNS layer in May 2025 (and earlier in 2022), Curve moved users to curve.finance 9.
Is Curve Finance the same as the Curve DAO token?
No. Curve Finance is the protocol and its apps. CRV, the "Curve DAO token", is its governance and reward token, and CRV must be locked as veCRV to vote 1215.
Who runs Curve?
veCRV holders govern it through the Curve DAO, and a 5-of-9 Emergency DAO has limited emergency powers 17. Michael Egorov created the protocol 1. curve.finance doesn't name an operating company 18.
How do veCRV holders earn from Curve?
They receive 90% of the converted admin fees, which are half of each pool's swap fee, plus most crvUSD borrow interest. Payouts are in crvUSD, weekly 1011.
What is crvUSD backed by?
Crypto collateral, such as ETH and BTC, deposited by borrowers on Ethereum, managed by smart contracts and DAO-set parameters 16.
Can I lose money providing liquidity to a stablecoin pool?
Yes. If one asset in the pool depegs, LPs are left holding more of it. Smart-contract and toolchain risk also apply, as the 2023 Vyper exploit showed 3.

Curve elsewhere on CoinPulse

Sources

  1. 1CryptoSlate, "Michael Egorov" profile —cryptoslate.com
  2. 2LlamaRisk / Curve, "Vyper nonreentrancy lock vulnerability" post-mortem —hackmd.io
  3. 3Vyper team, "Vyper nonreentrancy lock vulnerability technical post-mortem" —hackmd.io
  4. 4Nexus Mutual, "Curve Finance Loss Event (30 July 2023) | Claims Guide", updated 2023-08-07 —forum.nexusmutual.io
  5. 5Cointelegraph, "Alchemix reports return of all stolen funds from Curve pools", 2023-08-05 —cointelegraph.com
  6. 6Curve community blog, "August 10, 2022: Curve frontend hacked" —curve.substack.com
  7. 7Decrypt, "Curve 'strongly suggests' domain migration to Ethereum Name Service after $570K frontend hack", 2022-08 —decrypt.co
  8. 8Cointelegraph, "Curve founder repays bad debt after liquidation", 2024-06-13 —cointelegraph.com
  9. 9The Block, "Curve Finance's front-end targeted in DNS attack on website", 2025-05-13 —theblock.co
  10. 10Curve Docs, "Fee Architecture" map —docs.curve.finance
  11. 11Curve Docs, "Fee Collection, Burning, and Distribution" and "veCRV Revenue Share" — ;docs.curve.finance
  12. 12Curve Docs, "CRV" —docs.curve.finance
  13. 13ForkLog, "What is Curve?" —forklog.com
  14. 14Curve Docs, "Supported Chains & Assets" —docs.curve.finance
  15. 15Curve Docs, "What is veCRV?" —docs.curve.finance
  16. 16Curve Docs, "crvUSD" and "crvUSD risk disclaimer" — ;docs.curve.finance
  17. 17Curve Docs, "Security Audits" and "Security Practices" — ;docs.curve.finance
  18. 18curve.finance (interface) —curve.finance

Other decentralized exchangesAll →

What changed on this page

  • 2026-10-19Profile rewritten. Added the products beyond the DEX (crvUSD and its soft-liquidation mechanics, scrvUSD, LlamaLend), veCRV mechanics, the 18-network list, governance and Emergency DAO powers, and the audit history. Removed the unverified "Switzerland" location as a stated headquarters. 2026-10-19 (verification pass): Settled the July 2023 figures from the LlamaRisk/Curve post-mortem and the Nexus Mutual recovery summary: over $61M drained, with partial recovery that varied by pool. This replaces the old "73% (~$52M) recovered" claim. Added the August 2022 curve.fi DNS hijack (~$570K), the June 2024 founder-loan liquidations (~$10M bad debt) and the May 2025 X-account and DNS compromise. Fee flow confirmed from the docs.curve.finance fee map (50% admin fee; 10% treasury / 90% veCRV; ~15%/85% crvUSD interest split). Launch dates set to January 2020 (DEX) and August 2020 (CRV).
  • 2026-09-28Profile created: what Curve Finance is (disambiguated from the math/fashion senses), how its StableSwap AMM works, and the safety picture — the July 2023 Vyper-compiler reentrancy exploit (~$70M, ~73% recovered), plus DeFi-inherent and phishing risks.
All companies